Expectations met (again)
Nestlé delivered what the market expected in the first half of 2026. Sales growth and margins were in line with forecasts, meaning the Group has now met expectations for several consecutive quarters.
There is considerably more movement in the portfolio. For its mineral water business, Nestlé is founding an equally owned joint venture with private equity firm Platinum Equity, which is expected to generate billions for the Group in the first half of 2027. In addition, the food supplements and ice cream businesses are up for sale. Both generate below-average returns, and their sale should therefore provide a noticeable positive to the Group’s margin.
Going forward, Nestlé will focus more strongly on coffee and pet food, which together account for almost half of the revenues. At the same time, the cost-saving programme is running slightly ahead of plan. Notably, a significant proportion of the freed-up funds is being reinvested in advertising for brands with strong growth rather than being used to boost margins in the short term. The second half of the year is likely to be more challenging, although management is confirming its growth and margin targets. The comparison base has risen, as have expectations, while inventory reductions by US pet food retailers and the delisting of products by a major European customer are creating additional headwinds.
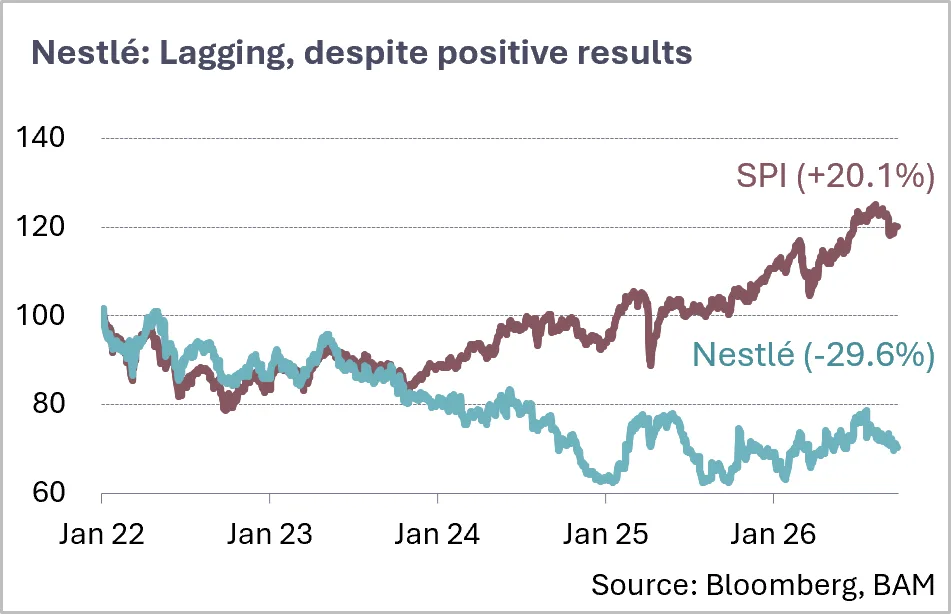
The share price has not reflected these positive developments. At current levels, Nestlé looks attractive, particularly as its dividend yield of 4.1% is well above the average for the broader Swiss equity market.